Jump to section
Try OnTheClock Free
Save time and make payroll effortless with our easy-to-use, affordable employee time tracking app.
Try It Free"In this world, nothing is certain except death and taxes."
Benjamin Franklin made that observation more than 200 years ago, and it's just as relevant today.
But not all taxes are created equal. Payroll taxes primarily fund Social Security, Medicare, and unemployment insurance, with employers and employees sharing certain costs. Income taxes, meanwhile, are based on taxable income and help fund government operations. Employees are responsible for their personal income taxes, although employers generally withhold those taxes from their paychecks.
Understanding the difference is important for employers who calculate payroll, manage tax obligations, and determine how much employees actually take home. Here's how payroll and income taxes compare, who pays each, and what the 2026 rates mean for your business.
Key takeaways:
-
Payroll taxes pay for Social Security, Medicare, and unemployment insurance. Employers and employees split Social Security and Medicare, and employers pay unemployment taxes.
- Income taxes fund a broad range of government services. Employees are responsible for personal income taxes on their wages, while employers generally withhold and remit those taxes.
-
In 2026, Social Security is 6.2% each for employers and employees on wages up to $184,500. Medicare is 1.45% each, with no cap.
-
On a $100,000 salary in Michigan, the employee pays about $24,819 in income and payroll taxes. The employer pays $7,692 plus state unemployment tax.
Payroll Tax vs. Income Tax at a Glance
| Category | Payroll Taxes | Income Taxes |
|---|---|---|
| What They Fund | Social Security, Medicare, and unemployment insurance | General federal, state, and local government services |
| Who Pays | Employers and employees generally share Social Security and Medicare taxes; employers usually pay unemployment taxes | Employees are responsible for their personal income tax; employers withhold and remit it |
| How Rates Work | Generally fixed rates, with wage limits and some additional taxes | Federal income tax is progressive; state and local systems vary |
| 2026 Federal Rates | Social Security: 6.2% each for employers and employees; Medicare: 1.45% each; federal unemployment tax (FUTA): generally 0.6% after the full credit | Seven federal individual income tax brackets ranging from 10% to 37% |
| Wage Limits | Social Security applies up to $184,500; Medicare has no wage cap | No overall wage cap; applicable rates depend on taxable income |
| Effect of Form W-4 | Generally does not change standard Social Security and Medicare (FICA) tax rates | Helps determine federal income tax withholding |
| Employer Reporting | Forms 941 and 940, along with applicable state unemployment filings | Federal income tax withholding is generally reported on Forms 941 and W-2 |
What Are Payroll Taxes?
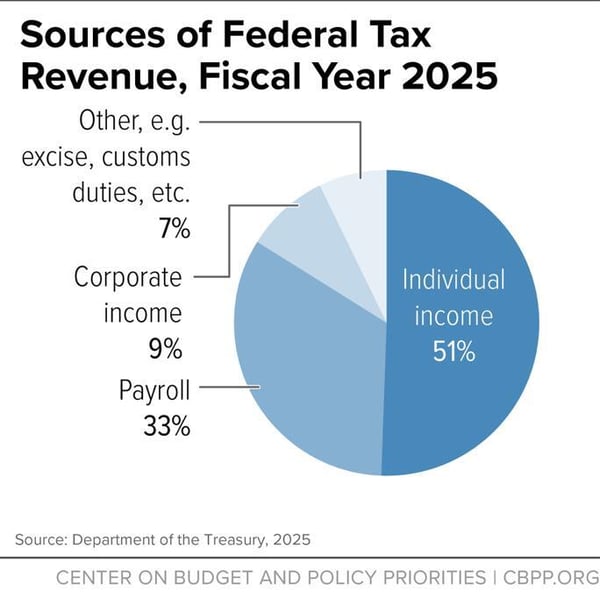
Payroll taxes are taxes collected on employee wages to fund specific government programs, primarily Social Security, Medicare, and unemployment insurance.
Unlike individual income taxes, payroll taxes generally use fixed percentages. Employers are responsible for withholding the employee's share of Social Security and Medicare taxes and contributing their own matching amounts.
Social Security and Medicare taxes are collectively known as Federal Insurance Contributions Act (FICA) taxes.
In 2026, the standard FICA rates are:
-
Social Security: 6.2% paid by the employee and another 6.2% paid by the employer, up to the annual wage limit.
-
Medicare: 1.45% paid by the employee and another 1.45% paid by the employer, with no annual wage limit.
That means most employees pay a combined FICA rate of 7.65%, which their employers match.
For example, consider an employee who earns $1,923.08 during a pay period:
-
Social Security: $1,923.08 × 6.2% = $119.23.
-
Medicare: $1,923.08 × 1.45% = $27.88.
-
Total employee FICA withholding: $147.11.
-
Employer's matching contribution: $147.11.
-
Combined employee and employer contribution: $294.22.
These calculations assume the employee's wages are fully subject to both taxes and no additional Medicare tax applies.
Employers also pay federal unemployment tax (FUTA) and state unemployment tax (SUTA). These taxes help fund unemployment compensation programs for eligible workers. Rates and wage limits vary, particularly at the state level.
Who Pays Payroll Taxes?
Both employers and employees are responsible for certain payroll taxes, but the amount each pays depends on the type of tax.
For Social Security and Medicare, employers and employees generally split the cost equally. Employees have 7.65% withheld from covered wages, while employers contribute an additional 7.65% from their own funds.
Federal unemployment tax (FUTA) is paid by employers, not withheld from employee wages. State unemployment taxes (SUTA) are also generally employer-funded, although Alaska, New Jersey, and Pennsylvania require certain employee contributions.
Self-employed individuals generally pay self-employment tax instead of having Social Security and Medicare taxes withheld by an employer. The standard rate is 15.3%, generally applied to 92.35% of net self-employment earnings, subject to the Social Security wage limit and applicable additional Medicare tax rules.
2026 Payroll Tax Rates and Wage Limits
Standard Social Security and Medicare tax rates generally remain the same regardless of an employee's filing status or federal income tax bracket. However, certain payroll taxes have annual wage limits, and the threshold for Additional Medicare Tax depends on the employee's filing status.
Here are the key federal payroll tax rates and limits for 2026:
| Payroll Tax | Employee Pays | Employer Pays | 2026 Wage Limit |
|---|---|---|---|
| Social Security | 6.2% | 6.2% | $184,500 |
| Medicare | 1.45% | 1.45% | No limit |
| Additional Medicare | Additional 0.9% on Medicare wages above the applicable filing-status threshold. | No employer match | Employers begin withholding above $200,000 |
| FUTA | None | 6%, generally reduced to 0.6% after the full credit | First $7,000 |
| SUTA | Usually none | Varies by state | Varies by state |
Social Security wage limit
In 2026, Social Security taxes apply to the first $184,500 of covered wages.
Once an employee reaches that amount, Social Security withholding generally stops for the remainder of the year with that employer. The employer's corresponding Social Security contribution also stops.
Medicare taxes, however, continue on all covered wages.
Additional Medicare Tax
Higher-income employees may owe an additional 0.9% Medicare tax when their Medicare wages exceed the applicable filing-status threshold.
For 2026, the thresholds are $200,000 for single filers, $250,000 for married couples filing jointly, and $125,000 for married individuals filing separately.
Employers must begin withholding Additional Medicare Tax when wages paid to an employee exceed $200,000 during the calendar year, regardless of filing status. Employers do not match this additional tax.
Federal unemployment taxes
The standard FUTA rate is 6% on the first $7,000 of an employee's annual wages.
Most employers qualify for a credit of up to 5.4%, reducing the effective federal unemployment tax rate to 0.6%. That generally results in a maximum annual FUTA obligation of $42 per employee, although credit-reduction rules may increase the amount.
State unemployment taxes
SUTA rates and wage bases vary by state. They may also depend on the employer's industry, unemployment claims history, and other state-specific factors. For a closer look at one state's rules, see our guide to California payroll taxes.
For employers operating in multiple states, these differences make accurate payroll tax calculations particularly important.
What Are Income Taxes?
Income taxes are taxes imposed on individuals and businesses based on taxable income or profits.
Unlike payroll taxes, which primarily fund specific programs, income taxes support a broader range of government expenses, including education, infrastructure, national defense, and public services.
For employees, income tax obligations generally depend on factors such as earnings, filing status, deductions, and available tax credits.
Income taxes can apply to several types of earnings, including:
-
Wages, salaries, bonuses, and commissions
-
Business profits
-
Interest and dividends
-
Rental and royalty income
-
Certain investment gains
-
Certain retirement distributions
-
Gambling winnings and other taxable income
The federal government uses a progressive income tax system, with seven individual income tax rates ranging from 10% to 37% in 2026.
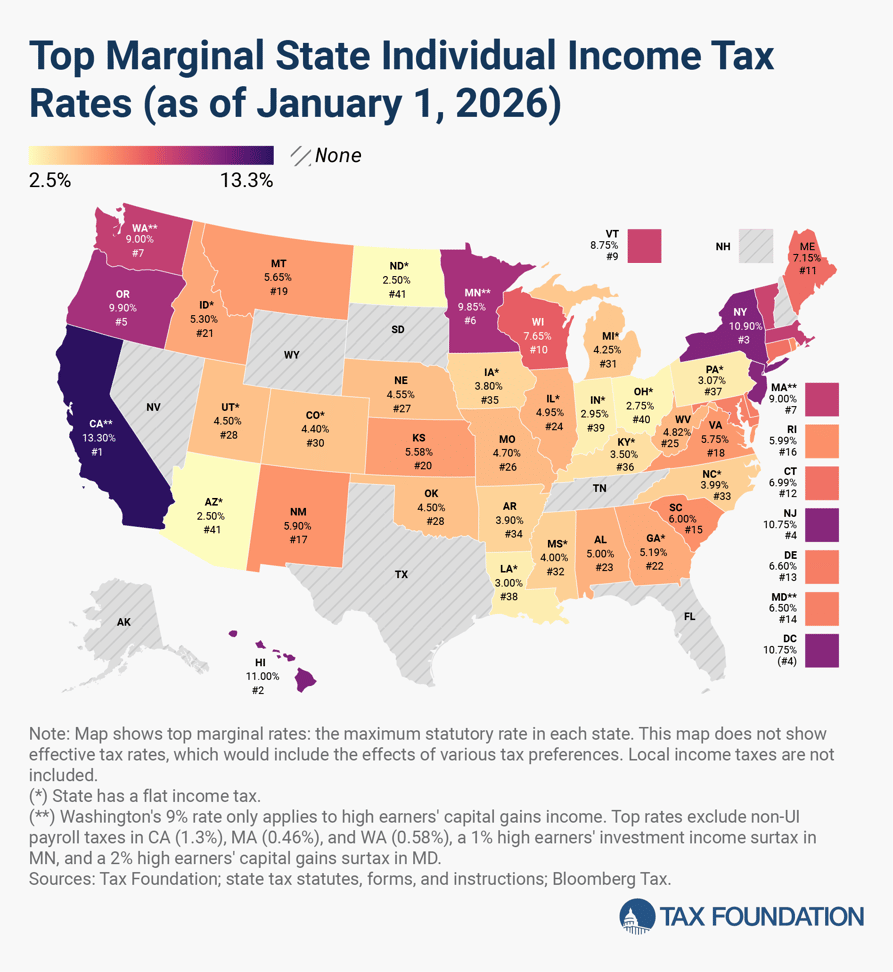
State income taxes work differently. Some states use progressive rates, others impose flat income taxes, and several states do not levy a broad-based individual income tax on wages.
For example, Michigan has a 4.25% individual income tax rate in 2026, while Florida and Texas do not impose an individual income tax on wages.
Employers generally withhold federal income tax from employee wages using the employee's Form W-4 information and applicable IRS withholding rules.
However, the amount withheld during the year isn't necessarily the employee's final tax liability. That amount is reconciled when the employee files a tax return.
Who Pays Income Taxes?
Employees are responsible for their personal income taxes, but employers generally handle the withholding and remittance process.
Each pay period, employers calculate the appropriate federal income tax withholding based on the employee's earnings, Form W-4, and applicable withholding methods.
The employer then submits the withheld amounts to the appropriate tax authorities.
State and local income tax withholding may also be required, depending on where the employee works or lives.
Unlike Social Security and Medicare taxes, employers do not match their employees' personal income tax withholding.
However, businesses may separately owe income taxes on their own profits, depending on their legal structure and tax treatment.
For example, a corporation may owe income tax on taxable corporate profits, while profits from certain pass-through businesses may be reported on the owners' individual returns.
Those taxes are separate from the personal income taxes withheld from employee paychecks.
Progressive vs. Flat Income Tax Rates
Income tax systems generally use either progressive or flat rates.
The main difference is how the tax percentage changes as taxable income increases.
Progressive Income Tax
A progressive income tax applies higher rates to higher portions of taxable income.
The federal individual income tax system uses this approach.
In 2026, federal income tax brackets for a single filer are:
| Tax Rate | Taxable Income |
|---|---|
| 10% | $0–$12,400 |
| 12% | Over $12,400–$50,400 |
| 22% | Over $50,400–$105,700 |
| 24% | Over $105,700–$201,775 |
| 32% | Over $201,775–$256,225 |
| 35% | Over $256,225–$640,600 |
| 37% | Over $640,600 |
One important distinction: Entering a higher tax bracket doesn't mean every dollar of income is taxed at that higher rate.
For example, someone whose taxable income places them in the 22% bracket pays 10% on the first portion, 12% on the next portion, and 22% only on the income within that bracket.
This is where two terms become important:
-
Marginal tax rate: The rate applied to the highest portion of taxable income.
-
Effective tax rate: Effective tax rate: Total income tax liability divided by the relevant income amount, such as taxable income or adjusted gross income. The denominator should be specified when comparing rates.
An individual's effective federal income tax rate is generally lower than their top marginal rate because income is taxed across multiple brackets.
Flat Income Tax
A flat income tax applies the same percentage rate to taxable income, regardless of how much someone earns.
For example, under a hypothetical 4% flat income tax:
- A taxpayer with $40,000 in taxable income would owe $1,600.
- A taxpayer with $100,000 in taxable income would owe $4,000.
Both taxpayers pay the same percentage, but they don't pay the same dollar amount.
This distinction is important. A flat income tax means a consistent rate, not an identical tax bill for everyone.
Michigan is one of the states that uses a flat individual income tax rate. Its 2026 rate is 4.25%, although allowable exemptions and other adjustments affect the final amount owed.
Payroll Tax vs. Income Tax: A $100,000 Salary Example for 2026
Understanding the different tax rates is one thing. Seeing how they affect an actual paycheck is another.
Consider a single employee in Michigan who earns $100,000 annually in 2026.
For this example, we'll assume:
- The employee is single and takes the $16,100 federal standard deduction.
- The employee has no additional income, federal deductions, or tax credits.
- All $100,000 is subject to standard Social Security and Medicare taxes.
- The employee qualifies for one $5,900 Michigan personal exemption.
- No additional Michigan deductions, credits, or local income taxes apply.
- The employer qualifies for the full FUTA credit and the employee is subject to the usual FUTA rules.
Federal Income Tax
The employee earns $100,000 but takes the $16,100 federal standard deduction.
That leaves $83,900 in federal taxable income.
Applying the 2026 federal income tax brackets for a single filer:
- First $12,400 taxed at 10% = $1,240
- Next $38,000 taxed at 12% = $4,560
- Remaining $33,500 taxed at 22% = $7,370
Estimated federal income tax: $13,170.
Payroll Taxes
Social Security and Medicare taxes are calculated separately from federal income tax.
For this employee:
- Social Security: $100,000 × 6.2% = $6,200
- Medicare: $100,000 × 1.45% = $1,450
Total employee FICA taxes: $7,650.
The employer also contributes $7,650 in matching Social Security and Medicare taxes.
Assuming the employer qualifies for the full FUTA credit and no credit reduction applies, federal unemployment tax is 0.6% of the first $7,000 in taxable wages, or $42. State unemployment tax costs depend on the employer's applicable rate.
Michigan Income Tax
Michigan's 2026 individual income tax rate is 4.25%.
For this example, we'll apply the state's $5,900 personal exemption to the employee's $100,000 in wages.
-
Michigan income: $100,000
-
Personal exemption: $5,900
-
Estimated Michigan taxable income: $94,100
-
Income tax: $94,100 × 4.25% = $3,999.25
This is a simplified estimate. Actual state tax liability may differ based on additional deductions, credits, other income, or individual circumstances.
Total Tax Summary
| Tax | Employee Pays | Employer Pays |
|---|---|---|
| Federal Income Tax | $13,170 | — |
| Social Security | $6,200 | $6,200 |
| Medicare | $1,450 | $1,450 |
| FUTA | — | $42 |
| Michigan Income Tax | $3,999.25 | — |
| SUTA | — | Varies by employer |
| Total Estimated Annual Taxes | $24,819.25 | $7,692 + SUTA |
Under these simplified assumptions, the employee's estimated annual federal and Michigan income taxes, combined with employee Social Security and Medicare taxes, total $24,819.25. Actual paycheck withholding may differ depending on Form W-4 elections, payroll frequency, and other applicable factors.
The employer would separately owe $7,692 in matching FICA and FUTA taxes, plus any applicable state unemployment taxes.
Assuming the employer qualifies for the full FUTA credit, the $100,000 salary would create an estimated minimum annual employment cost of $107,692, including matching FICA and FUTA taxes but excluding SUTA, benefits, workers' compensation insurance, and other employment expenses.
This example illustrates the fundamental difference between payroll and income taxes.
Income taxes are the employee's personal responsibility. Payroll taxes can create costs for both the employee and the employer.
How Can I Simplify the Tax Process?
Per Benjamin Franklin, if you're still breathing, that means you're inching toward a tax deadline.
For business owners, calculating payroll and income taxes involves more than understanding which rates apply. You also need accurate employee records, correct withholding amounts, timely tax deposits, and proper reporting. Our payroll taxes and compliance guide walks through each step.
The process becomes more complicated when employees earn different wages, work overtime, or live and work in different states.
Managing these responsibilities manually can create opportunities for costly mistakes, including incorrect withholding, missed deadlines, and inaccurate payroll records.
Fortunately, payroll software can help reduce the administrative burden.
OnTheClock combines employee time tracking, scheduling, PTO management, and optional built-in payroll in one platform.
Employers can track hours, calculate employee time, manage payroll information, and reduce the need to transfer the same data between multiple systems.
For businesses using OnTheClock Payroll, integrated payroll processing can also help manage applicable tax calculations, withholding, and reporting requirements.
Automation doesn't eliminate an employer's legal responsibilities, but it can make the process easier to manage while reducing avoidable manual errors.
Start your free 30-day OnTheClock trial and see how much easier payroll management can be.
Frequently Asked Questions
What Is the Difference Between Payroll Taxes and Income Taxes?
Payroll taxes primarily fund Social Security, Medicare, and unemployment insurance. Employers and employees share certain payroll taxes, while employers generally pay unemployment taxes. Income taxes are based on taxable income and support broader government expenses. Employees owe personal income taxes, which employers generally withhold from their wages.
Are Payroll Taxes the Same in Every State?
No. Federal Social Security and Medicare rates generally apply nationwide, but state unemployment taxes vary by location. Some states also require employee contributions to certain payroll-related programs. Employers should review applicable state and local requirements when calculating payroll taxes.
Which Payroll Taxes Are Paid by Employers?
Employers generally contribute 6.2% of covered wages toward Social Security and 1.45% toward Medicare, matching their employees' standard FICA taxes. They also pay federal unemployment taxes and, in most states, state unemployment taxes.
Do Employers Pay Income Tax?
Employers generally don't pay their employees' personal income taxes. Instead, they withhold applicable income taxes from employee wages and remit those amounts to the appropriate tax authorities. Businesses may separately owe income taxes on their own profits, depending on their structure and tax treatment.
What Is FICA, and Why Is It Important?
FICA stands for Federal Insurance Contributions Act. These taxes fund Social Security and Medicare. Employees generally pay a combined 7.65% on covered wages, which employers match, subject to the Social Security wage cap and applicable Medicare tax rules.
What Is FIT Tax?
FIT stands for federal income tax. Employers generally withhold FIT from employee paychecks based on earnings, Form W-4 information, and applicable withholding rules. The amount withheld is credited toward the employee's federal income tax liability when the employee files a tax return.
Do Payroll Taxes Reduce Taxable Income?
Employee Social Security and Medicare taxes generally don't reduce federal taxable income. However, certain pretax deductions and benefits can reduce wages subject to income taxes or payroll taxes. For example, traditional 401(k) contributions generally reduce federal income-taxable wages but not Social Security or Medicare wages.
Do Most Workers Pay More in Payroll Taxes Than Income Taxes?
It depends on earnings, filing status, deductions, and tax credits. Some lower-income workers may pay more in Social Security and Medicare taxes than federal income taxes, while higher-income workers may owe substantially more in income tax. The two taxes use different rates and calculation methods.
Are Payroll Taxes Paid to the IRS?
Federal payroll taxes, including Social Security, Medicare, and FUTA, are generally reported and paid through the IRS. Employers pay state unemployment taxes to the appropriate state agencies. Federal income tax withholding is also remitted to the IRS.
What Taxes Come Out of My Paycheck?
Most employee paychecks include federal income tax withholding and Social Security and Medicare taxes. State or local income taxes may also apply. Other payroll deductions, such as insurance premiums and retirement contributions, can reduce take-home pay but aren't necessarily taxes.